This side-by-side comparison table clarifies key distinctions between additional insured endorsements and certificate of insurance checkboxes for policy holders, third-party vendors, and administrative teams managing compliance folders. Many parties mistakenly assume a checked box on a standard ACORD 25 certificate grants the same liability coverage as a formal endorsed amendment to the underlying policy, a misstep that can lead to denied coverage during a claim. This resource is framed for educational use only per Clause Shelf guidelines, and no content on this page binds coverage or replaces consultation with a licensed insurance professional.
Endorsement Form Coverage Eligibility Specifications
An additional insured endorsement is a formal, carrier-filed amendment to a commercial general liability (CGL), commercial auto, professional liability, or workers’ compensation policy that adds a named third party as eligible for coverage under the policy’s terms. Eligibility specifications require the endorsement to list the full legal name of the additional insured, specify the scope of coverage (e.g., ongoing operations only, completed operations, or limited to a specific project address), include effective and expiration dates aligned with the associated contract or project timeline, and bear the signature of an authorized representative of the issuing carrier, not just a third-party broker or independent agent. Endorsements are categorized as either scheduled (listing a specific individual or entity) or blanket (covering all parties the policy holder is contractually obligated to add, with no need for individual scheduled filings for each vendor), but both types must be formally processed and stored in the carrier’s official policy records to be valid. Eligibility for coverage under an endorsement only applies to claims that arise from the policy holder’s negligence or covered activities, as outlined in the endorsement language, so it is critical to review the full text of the document to confirm it matches the contractual obligations between the policy holder and the additional insured. Illustrative example: a general contractor requires a subcontractor to add them as an additional insured for a 6-month commercial build, so the subcontractor’s carrier issues an endorsement listing the GC’s full legal name, project address, and coverage limited to claims arising from the subcontractor’s work on that site during the 6-month period.
Certificate Checkbox Binding Authority Limitations
A certificate of insurance (COI) is a snapshot of policy status at the time of issuance, not a formal amendment to the underlying policy. The pre-printed “additional insured” checkbox on standard COI forms is designed for the issuing agent to indicate that a valid additional insured endorsement already exists in the policy file, not to grant new coverage to the certificate holder. Binding authority limitations apply to nearly all independent agents and brokers, who do not have the authority to amend policy terms or add additional insureds via a COI checkbox alone; only the carrier’s underwriting team can formally modify policy terms, so any checkbox indication is only as valid as the underlying endorsement that exists on file with the carrier. Many widely used COI forms, including the ACORD 25, include explicit fine print disclaimers that state “This certificate is issued as a matter of information only and confers no rights upon the certificate holder. This certificate does not amend, extend or alter the coverage afforded by the policies below.” This means even if the agent checks the additional insured box, that checkmark has no legal weight without the supporting endorsement, and the carrier is not obligated to honor a claim from a third party that only has a checked box on a COI. In some cases, agents may check the box as a courtesy if the policy holder has requested an endorsement, but if the endorsement has not been fully processed and approved by the carrier, the checkmark is not valid.
Comparison Table Columns for Liability Boundaries
The table below outlines core liability boundary differences between formal additional insured endorsements and standalone COI checkboxes, with documentation requirements for compliance folder tracking:
| Coverage Attribute | Formal Additional Insured Endorsement | COI Additional Insured Checkbox | Required Supporting Documentation |
|---|---|---|---|
| Binding Coverage Status | Formally amends underlying policy terms, is legally binding on the issuing carrier | Does not alter policy terms, is not legally binding as a standalone document | Endorsement requires carrier-approved signed amendment; checkbox requires cross-reference with a valid endorsement on file |
| Third Party Eligibility for Claim Defense | Named additional insured is explicitly eligible for defense costs and covered damages per endorsement terms | No eligibility for defense or damages unless a corresponding endorsement exists to confirm coverage | Eligibility requires copy of the full endorsement for third party files; checkbox only requires COI copy for preliminary compliance tracking |
| Scope of Coverage Clarity | Explicitly lists coverage limits, project restrictions, effective/expiration dates, and excluded activities | Provides no detail on coverage scope, only indicates that an endorsement may exist on file | Scope verification requires full endorsement text; checkbox requires follow-up with issuing agent to confirm endorsement details |
| Carrier Notification Requirement | Endorsement is filed directly with carrier underwriting team and stored in official policy records | Checkbox mark is often not reported to the carrier, only stored in agent or broker files | Carrier confirmation requires written request for policy endorsement verification; checkbox confirmation requires agent sign-off that endorsement is on file |
| Validity During Policy Cancellation | Endorsement remains valid for covered claims occurring during the endorsement effective period, even if policy is later canceled | Checkbox has no standalone validity, and COI status only reflects policy status at time of issuance | Cancellation protection requires endorsement with 30-day notice provision for additional insureds; checkbox provides no cancellation notification rights |
Issuing Agent Note Validation Protocols
For any COI submitted with a checked additional insured box, administrative teams should follow standardized validation protocols to confirm coverage eligibility before marking the submission as compliant in their folder. First, submit a written request to the issuing agent for an official letterhead note confirming that a valid, carrier-endorsed additional insured form is on file with the carrier, matches the third party’s full legal name, and aligns with the coverage requirements outlined in the associated vendor or service contract. Next, cross-reference the agent’s license number listed on the note with your state’s insurance department database to confirm their active licensing status and binding authority for the issuing carrier. The agent’s note should explicitly specify the endorsement number, effective and expiration dates, and coverage scope to match the terms of your signed agreement. If the agent provides a validation note, you should also request a clause that the agent will notify you within 10 business days if the endorsement is canceled, revoked, or modified before its expiration date, adding an extra layer of protection against gaps in coverage. If the agent is unable to provide a formal endorsement copy and signed validation note within 10 business days of your request, flag the COI as non-compliant in your folder until supporting documentation is received. If the agent refuses to provide requested documentation, require the policy holder to obtain a new COI and endorsement from a different licensed agent or carrier to avoid uncompensated liability exposure. Illustrative example: a property manager receives a COI from a cleaning vendor with the additional insured box checked, so they send a request to the issuing agent for a copy of the full endorsement and a signed note confirming the endorsement is filed with the carrier, with coverage applicable to all cleaning work performed at the property address for the duration of the 12-month service contract.
Policy Holder Folder Retention Mandates
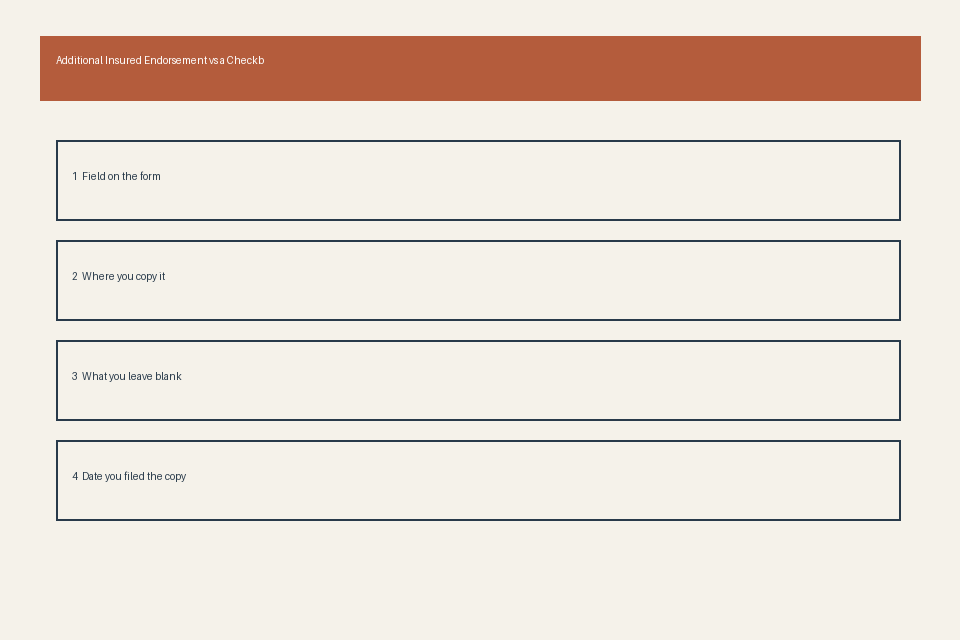
All documentation related to additional insured endorsements and COIs must be stored in a centralized compliance folder, either physical or encrypted digital, for the full duration of the policy period plus the applicable statute of repose for your state and industry, which typically ranges from 3 to 10 years after the completion of work or termination of the associated contract. For formal additional insured endorsements, retain a signed, dated copy of the full endorsement, written carrier confirmation of filing, and any amendments to the endorsement terms requested during the coverage period. For COIs with a checked additional insured box, retain the original COI, the agent’s signed validation note, a full copy of the corresponding endorsement, and any written carrier confirmation of endorsement status if requested. Retain all email or written correspondence related to requests for endorsement copies or validation, as these records may be required to resolve claim disputes that arise years after the project or contract ends. If you are listed as the additional insured, store these documents separately from the policy holder’s files, as you may not have access to the policy holder’s records if a claim arises after the contract ends. For digital folders, all documents should be saved in a read-only format to prevent accidental modification, and backed up to a secure cloud storage system with access limited to authorized compliance staff only. For physical folders, all documents should be stored in a locked filing cabinet in a climate-controlled facility to prevent damage from water, fire, or pests. Standardized folder retention checklists are available for reference via Clause Shelf for teams that need to align retention protocols with industry compliance requirements. Conduct an annual audit of your compliance folder to confirm that all endorsements and COIs are up to date, and that any expired policies are replaced with new documentation before the previous coverage expires.
Your immediate next step is to pull all COIs with checked additional insured boxes from your compliance folder and submit a request for the corresponding formal endorsement and agent validation note within 3 business days.