This side-by-side comparison breaks down core differences between two common commercial liability additional insured endorsement formats. Scheduled additional insured entries list each party by full legal name on a specific endorsement form, while blanket provisions extend coverage automatically to eligible third parties that meet pre-defined eligibility criteria. This page is for reference only, does not constitute legal or coverage advice, and you should confirm all terms with your licensed insurance broker or policy issuer before submitting requests for either endorsement type. Clause Shelf provides fillable form templates for both endorsement types to standardize your request submissions to carriers.
Endorsement form fields for scheduled additional insured entries
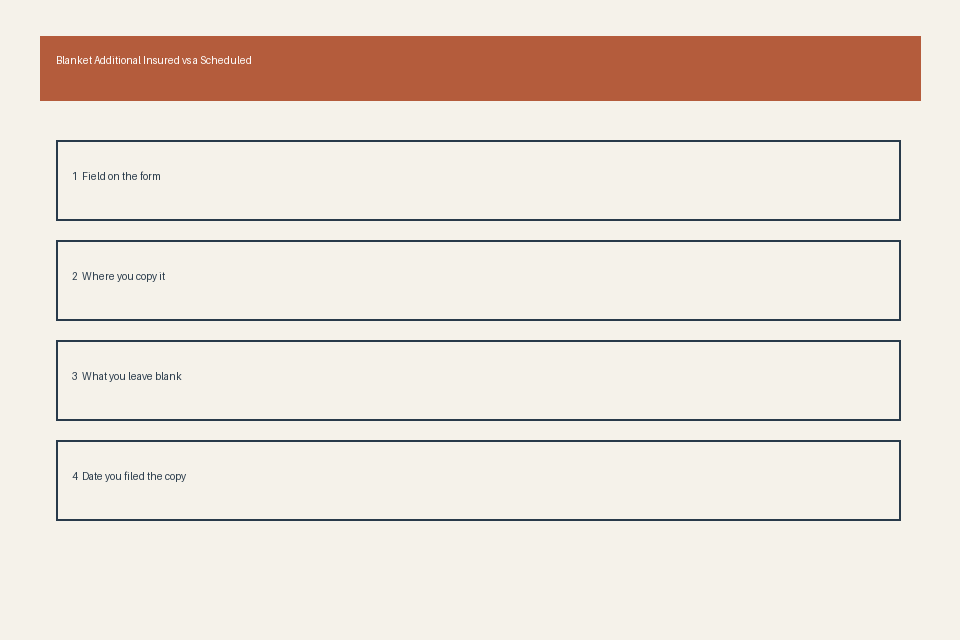
Scheduled additional insured endorsements require standardized fields to be completed for every party added to your policy, with no room for ambiguous or partial entries. Required fields typically include the full legal name of the third party (matching exactly the name on their underlying contract with your business), their official mailing address for claim correspondence, their federal tax ID number if requested by your carrier, the specific project or service scope tied to their coverage, the start and end dates of their coverage aligned with their contract term, and any allocated coverage limits if you are splitting policy limits across multiple scheduled parties. Each new scheduled entry requires a separate written request to your carrier, and most carriers charge an administrative fee for each addition or modification to a scheduled endorsement. You should store a physical copy of every updated scheduled endorsement in a dedicated subfolder of your primary policy file, so you can quickly cross-reference entries when responding to certificate of insurance (COI) requests or claim inquiries.
| Category | Scheduled Additional Insured | Blanket Additional Insured |
|---|---|---|
| Request Submission Timeline | 3-10 business day standard processing for each new party request, with possible delays if required supporting documentation is missing | 1-time processing when the endorsement is added to the policy, no additional wait time for parties that meet pre-approved eligibility criteria |
| Eligibility Verification Requirements | Requires submission of the party’s full legal name, mailing address, and a copy of the underlying signed contract confirming the need for additional insured status | Only requires confirmation that a party meets pre-defined policy criteria (e.g., active signed subcontract for work completed during the policy term) at the time a COI is issued |
| Endorsement Update Frequency | Requires a new endorsement filing every time a party is added, removed, or their contract term or scope of work changes | Only requires updates if the core eligibility rules for the blanket provision are modified by you or your carrier |
| Certificate of Insurance Processing Time | Requires a custom COI draft tailored to the named party, often taking 2-5 business days to process and approve from your carrier | Allows instant issuance of pre-approved COI templates for eligible parties, no custom carrier review required for standard requests |
| Coverage Scope Limitation Clarity | Limitations are explicitly tied to the named party and associated project directly in the endorsement text, with no cross-referencing required | Limitations are tied to general eligibility rules, which may require cross-referencing multiple policy sections to confirm coverage applies to a specific party |
*All timeline values listed are illustrative examples only, actual processing times vary by carrier and request volume.
Coverage schedule blocks for blanket additional insured eligibility
Blanket additional insured endorsements include dedicated coverage schedule blocks that outline the exact, non-negotiable criteria a third party must meet to qualify for automatic coverage under your policy. Common eligibility criteria listed in these blocks include holding a fully executed written contract with the named insured for services completed during the active policy period, maintaining their own active general liability policy with limits equal to or higher than a pre-specified threshold outlined in the schedule, providing a valid COI to the named insured before starting any work, and operating strictly within the scope of work outlined in their signed contract. Any party that fails to meet all listed criteria cannot access coverage under the blanket provision, and must be added as a scheduled additional insured if you are contractually obligated to extend them coverage. You should highlight these eligibility criteria with a colored sticky note in your policy document, so you can quickly verify a party’s eligibility when they request a COI, avoiding incorrect representations of coverage that could lead to claim denials or breach of contract allegations.
Policy declaration columns listing insured party inclusion rules
Your commercial liability policy declarations page includes a dedicated column for additional insured inclusion rules, which specifies whether your policy uses scheduled, blanket, or a combination of both additional insured formats. For policies using only scheduled entries, this column will note that all additional insureds are explicitly listed on attached endorsement forms, and no unlisted parties are extended any coverage under the policy. For policies using only blanket provisions, this column will reference the attached blanket additional insured endorsement form number, and note that all parties meeting the eligibility criteria in that form are included without separate listing. If your policy uses a combination of both formats, the column will specify the line of business or coverage type tied to each format, for example, scheduled additional insureds for long-term client contracts with total values over Illustrative example: $1 million, and blanket coverage for short-term subcontractors working on small residential projects. You should cross-reference this column with your attached endorsement forms at least quarterly to confirm all rules are accurately documented, and file any updated declarations pages in your primary policy folder immediately upon receipt from your carrier.
Certificate of insurance notes specifying additional insured type
When you issue a COI to a third party, the additional insured notes section must clearly state whether the party is covered under a scheduled or blanket endorsement, to eliminate confusion during claim processing and ensure compliance with the third party’s contract requirements. For scheduled additional insureds, the note should include the exact endorsement number where the party’s name is listed, and the specific effective and expiration dates of their coverage tied to their contract. For blanket additional insureds, the note should reference the blanket endorsement number, and include a line confirming that the party meets all eligibility criteria outlined in that endorsement as of the COI issuance date. Many certificate holders require specific standardized language in this section to accept the COI for contract compliance purposes, so you should keep a copy of every COI issued in a separate subfolder in your policy file, along with any supporting documentation of eligibility for blanket coverage requests. Clause Shelf has standard COI note templates for both endorsement types to ensure compliance with common certificate holder requirements.
Endorsement addendum boxes marking coverage scope limitations
Both scheduled and blanket additional insured endorsements include optional addendum check boxes that you can select to limit coverage scope to specific use cases, preventing you from overextending your policy limits or providing coverage that falls outside your contractual obligations. For scheduled endorsements, common limitation boxes include coverage limited exclusively to the specific project listed on the endorsement, coverage limited only to claims arising from the named insured’s proven negligence, and coverage limited strictly to the term of the underlying contract with the additional insured. For blanket endorsements, common limitation boxes include coverage limited to subcontractors that have provided written proof of their own active liability insurance, coverage limited to projects with a total value under a specified threshold, and coverage excluded for claims related to professional services or intentional acts. You should review these boxes carefully with your broker when requesting an endorsement, and confirm that all checked limitations align with the requirements of your underlying contracts, to avoid breach of contract claims or unexpected coverage denials. Keep a copy of all signed endorsement addendums in your policy file, and cross-reference them when issuing COIs to ensure you do not misrepresent coverage scope to third parties.
Your practical next action is to pull your current commercial liability policy declarations page and attached additional insured endorsements, mark whether you use scheduled, blanket, or combined coverage, and store a one-page reference sheet with this information in the front of your policy folder for quick access during COI requests.