This auto deductible type identification card lists coverage-specific out-of-pocket costs to reference when submitting an auto claim. You can store this document in your vehicle’s glove compartment or wallet alongside your insurance ID card to avoid misstating deductible amounts during first notice of loss calls. All fields align with standard auto insurance policy formatting, so you can cross-reference values directly with your declarations page without translating industry jargon. Clause Shelf provides this template for personal record-keeping only, and it does not modify your existing coverage terms or replace official policy documents issued by your carrier.
Card front printed field for collision deductible value display
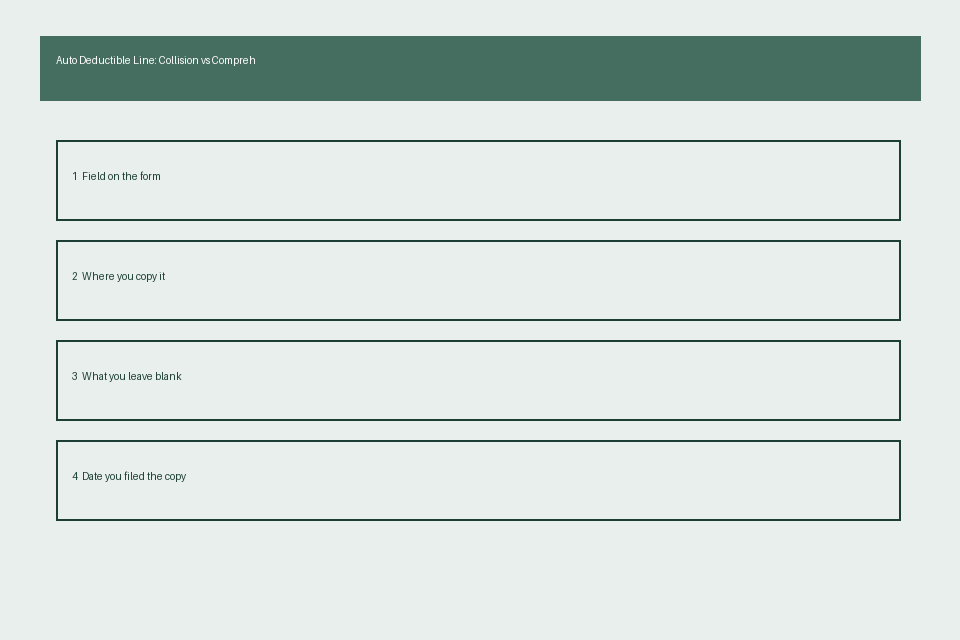
For collision coverage, the deductible applies any time your vehicle sustains damage from a crash with another vehicle, a fixed object like a guardrail or street sign, or a single-car rollover event, regardless of fault in states with no-fault auto insurance rules. The front-of-card field is printed in bold, high-contrast ink to ensure visibility in low-light conditions, such as if you are exchanging information at an accident scene after dark. You should update this field immediately if you adjust your collision deductible during a policy change, for example if you raise your deductible to lower your monthly premium, or lower it after paying off your vehicle loan. Illustrative example: if you increase your collision deductible from $500 to $1,000 at your six-month policy renewal, you cross out the old value with a single line, write the new value next to it, and add your initials and the date of the policy change to avoid conflicting values being referenced during a future claim. All entries should match exactly the values listed on your declarations page, and if you are unsure of the correct amount, you should reach out to your insurance issuer or licensed broker for confirmation before filling out the field.
Back card added note for comprehensive deductible breakdowns
Comprehensive coverage applies to damage that is not caused by a collision, including theft, vandalism, hail, wind, fire, flood, falling objects like tree branches, and collisions with wild animals like deer or coyotes. Many policies include variable deductibles for specific comprehensive perils, especially in regions prone to severe weather events like hailstorms, where carriers may offer lower premiums in exchange for a higher hail-specific deductible. The back-of-card note section has 6 pre-printed bullet points for you to list these peril-specific deductibles, so you do not have to look up the details in your full policy document during a stressful claim event. You can also note any coverage limits that apply to specific comprehensive perils in this section, for example if your policy only covers up to $2,000 of custom audio equipment theft with a separate $100 deductible for that coverage line. Always cross-reference any notes you add in this section with your official policy documents to ensure accuracy, and if you have questions about how deductibles apply to specific perils, contact your policy issuer for clarification.
Deductible value column for glass coverage cost listings
Glass coverage is often included as a line item under comprehensive coverage, but many carriers offer separate glass-only coverage riders that waive deductibles for minor repairs to reduce the number of full replacement claims filed. The dedicated glass column on the front of the card splits values by repair and replacement, as most policies have different deductible rules for these two service types: minor stone chip repairs are often 100% covered with no out-of-pocket cost, while full windshield replacement may require you to pay your full comprehensive deductible unless you carry a separate glass rider. This split column eliminates the common mistake of assuming all glass work is subject to the same deductible, which can lead to unexpected costs when you schedule service with an auto glass vendor. The standardized fields on the full card are outlined in the table below to make filling out your personal card simple and consistent with standard policy formatting.
| Card Section | Coverage Type | Pre-Filled Field Label | Field Entry Instructions | Allocated Space Dimensions |
|---|---|---|---|---|
| Front Top Right | Collision | Collision Deductible Amount | Enter exact numeric value from your official policy declarations page, include only the $ symbol and whole dollar amount, no cents or abbreviations | 1 inch x 2 inches |
| Back Top Lined Section | Comprehensive | Base Comprehensive Deductible + Peril-Specific Adjustments | List your standard comprehensive deductible first, then add bullet points for any peril-specific deductible variations (e.g., hail, custom parts theft, animal strike) as outlined in your policy | 3 inches x 2 inches |
| Front Middle Left Column | Glass | Glass Repair Deductible | Enter $0 if your policy includes full waiver of deductibles for minor glass repairs, otherwise enter the per-claim deductible amount specified for glass repair work | 1 inch x 1.5 inches |
| Front Middle Right Column | Glass | Glass Replacement Deductible | Enter the per-claim deductible for full windshield or window glass replacement, if different from your repair deductible, to avoid billing disputes with auto glass vendors | 1 inch x 1.5 inches |
| Back Bottom Section | All Coverage Types | Policy Reference + Effective Date | Enter your full auto insurance policy number (matching your printed ID card) and the start date of your current policy term to confirm listed values are active | 2 inches x 1 inch |
Coverage type tick box for quick deductible category sorting
The left edge of the card front has three pre-printed tick boxes corresponding to collision, comprehensive, and glass coverage. When you are filing a claim, you can tick the relevant box before sharing the card with your adjuster or repair shop to eliminate confusion about which coverage type applies to your current claim. For example, if you hit a deer, you tick the comprehensive box before submitting your damage estimate, so the repair shop billing team knows to apply the correct deductible to your invoice instead of defaulting to the higher collision deductible that many policies carry. You can pre-mark boxes for coverage types you do not carry with a large X, so you do not accidentally file a claim for a coverage that is not active on your policy. For example, if you drive an older vehicle that is worth less than $3,000, you may have dropped collision and comprehensive coverage to reduce costs, so you can X out those two boxes to remind yourself that only liability coverage is active, and any damage to your own vehicle will not be covered. If you have multiple vehicles on a single policy, you can print a separate card for each vehicle and mark coverage differences clearly on each card, for example if your new SUV has full collision, comprehensive, and glass coverage, but your old pickup only has liability coverage. This sorting feature reduces processing delays for claims, as adjusters and billing teams do not have to look up your coverage type to apply the correct deductible to your claim.
Wallet sleeve storage slip for card protection during travel
The identification card comes with a perforated, water-resistant plastic sleeve slip that fits in standard wallet card slots or vehicle glove compartment organizers, to prevent smudging of handwritten values or tearing of the card during regular access. The sleeve is designed to withstand the temperature fluctuations common in vehicle glove compartments, which can cause paper documents to warp, fade, or tear over time. The sleeve has a clear front and opaque back, so you can view the front of the deductible card without removing it from the sleeve, and you can tuck your official insurance ID card and vehicle registration card in the back pocket of the sleeve to keep all critical vehicle documents in one place. If you frequently rent vehicles or drive for work, you can print a second card and keep it in your work bag or wallet, so you have access to your deductible information even if you are not driving your personal vehicle. You should store old copies of your deductible card in your home auto insurance claim file, organized by policy term, so you have a record of your deductible values if you need to reference them for a past claim that is still being processed, or if you are comparing policy costs across renewal periods. Clause Shelf offers a separate folder template for auto insurance claim records that you can use to organize these old cards alongside claim forms, repair estimates, and correspondence with your carrier.
Print your free deductible-type identification card template, cross-reference all entered values with your most recent auto policy declarations page, and store the completed card in the included sleeve with your vehicle’s insurance ID card before your next trip.